AI Labs Valuation Pie Chart (Mid-2026)
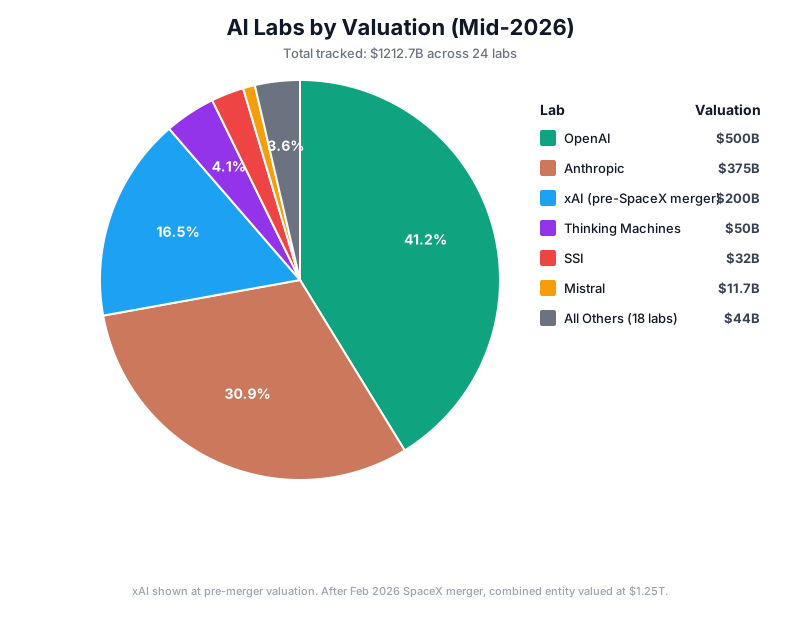
What this chart shows
A visual breakdown of how ~$1.21 trillion in AI lab valuations is distributed across the 24 standalone foundation model and AI research labs tracked publicly in mid-2026.
The headline finding
The top 3 labs control 88.6% of all tracked AI lab value.
- OpenAI alone: 41.2% ($500B)
- Anthropic: 30.9% ($375B)
- xAI (pre-SpaceX merger): 16.5% ($200B)
- Everyone else combined: 11.4% ($138B across 21 labs)
This is more concentrated than even the most consolidated tech markets in history. For comparison:
- Cloud (AWS + Azure + GCP): top 3 control ~65% of revenue
- Smartphones (Apple + Samsung): top 2 control ~35% of units
- Search (Google): controls ~90% of queries
AI lab valuations sit between cloud-style oligopoly and search-style monopoly — but with the added oddity that the top 3 are all unprofitable and burning cash.
Tier breakdown
| Tier | Threshold | Count | Combined Value | Share |
|---|---|---|---|---|
| 1 | $100B+ | 3 | $1,075B | 88.6% |
| 2 | $10-100B | 3 | $93.7B | 7.7% |
| 3 | $1-10B | 16 | ~$44B | 3.6% |
| 4 | <$1B | 2 | ~$0.5B | <0.1% |
What the chart understates
Hyperscaler internal AI labs aren't shown because they don't trade separately. If you valued them as standalone businesses:
- Google DeepMind would be ~$500B-$1T (would be #1 or #2)
- Meta AI/FAIR would be ~$300-500B (would be top 4)
- Apple AI, Amazon AGI, Microsoft AI all material
So the "real" AI lab landscape concentration is even more extreme than this chart shows — there are arguably 5-6 entities in the trillion-dollar tier, not 3.
Stealth labs reshaping the picture
SSI (Safe Superintelligence) at ~$32B with no product is the most notable anomaly. If they raise at the reported $50B+ next round, they jump into tier 2 alongside Mistral and Thinking Machines despite shipping nothing.
Thinking Machines at ~$50B, also barely shipping, is a similar bet on team quality (Mira Murati + ex-OpenAI research talent) over revenue.
These two represent ~$80B+ of valuation pricing thesis rather than business — the binary bets where outcomes are dramatically right or dramatically wrong.
What's likely true 24 months out
- Top 3 stay in top tier. OpenAI, Anthropic, xAI/SpaceX entrenched.
- Tier 2 consolidates upward or sideways. SSI either becomes top tier or fails. Thinking Machines likely finds a defensible lane. Mistral acquired or formalized as European sovereign AI.
- Tier 3-4 mostly attrites. Of 18 labs in tier 3-4, expect ~10-12 to be acquired or fold by 2028. A few specialized winners emerge (World Labs in spatial, Periodic in scientific, Black Forest in image).
- Chinese cohort consolidates. From 6 frontier labs (DeepSeek, Moonshot, Zhipu, Baichuan, 01.AI, MiniMax) down to 2-3 national champions.
- SpaceX IPO June-July 2026 at ~$1.5-1.75T re-rates the entire private AI comp set.
Important caveats
- All valuations are stale fast. SSI went from $5B (June 2024) → $32B (April 2025) → reportedly $50B+ (late 2025) in 18 months.
- Private valuations vary by source. Last primary round vs. secondary trades vs. reported-but-not-closed give different numbers.
- Chinese lab valuations are particularly opaque. Most numbers come from Chinese press conversions.
- Stealth labs by definition aren't on this list. SSI and Periodic make it because they've had public funding rounds; there may be 5-10 other well-funded stealth labs operating below public visibility.
- The chart excludes: application companies (Cursor, Lovable, Replit), AI infrastructure (CoreWeave, Lambda), vertical AI specialists, and hyperscaler internal divisions.
Companion to the full ranked list: AI Labs Ranked by Valuation (Mid-2026)
No redactions applied.
Published via wiis. Originals are encrypted at rest; this page reflects the redacted version. report abuse.
Discussion
No comments yet.